

Crypto tax in India remains strict in 2026. Profits earned from selling or transferring Bitcoin, Ethereum, stablecoins, NFTs, and other virtual digital assets are generally taxed at a flat rate of 30%. Surcharge and a 4% health and education cess may also apply.
A separate 1% tax deducted at source, or TDS, may be collected when crypto is transferred. Beginners should understand that TDS is deducted from the transaction value, while the 30% tax applies to taxable profit. These are separate parts of India’s crypto tax system.
What Is Considered Crypto Under Indian Tax Rules?
Indian income-tax rules use the term Virtual Digital Asset, commonly shortened to VDA.
VDAs generally include:
- Bitcoin and other cryptocurrencies
- Stablecoins
- Non-fungible tokens
- Similar notified digital assets
Indian currency, foreign currency, central bank digital currency, and certain notified assets are excluded from this definition.
The rules apply to income earned from transferring a VDA. A transfer may include selling crypto for Indian rupees, exchanging one crypto asset for another, or using crypto in another transaction that changes ownership.
Crypto Profits Are Taxed at 30%
Income from transferring a virtual digital asset is taxed at a flat rate of 30%. This rate applies regardless of how long the asset was held.
Unlike some traditional investments, crypto does not receive separate short-term and long-term tax rates under the VDA system. The taxable amount is generally calculated by subtracting the cost of acquisition from the sale consideration.
Simple Crypto Tax Example
Suppose you purchased Bitcoin for ₹1,00,000 and later sold it for ₹1,40,000.
Your profit would be:
₹1,40,000 − ₹1,00,000 = ₹40,000
The basic crypto tax would be:
30% of ₹40,000 = ₹12,000
A 4% health and education cess may then apply to the calculated tax. Surcharge may also apply when the taxpayer’s total income crosses the relevant limits.
This example does not include other income, deductions, surcharge calculations, or advance-tax obligations.
Only the Purchase Cost Is Normally Deductible
India’s crypto tax rules allow taxpayers to deduct the cost of acquiring the virtual digital asset when calculating income from its transfer.
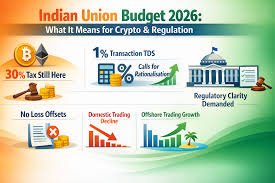
Other expenses generally cannot be deducted under Section 115BBH. These may include:
- Internet expenses
- Advisory charges
- Mining equipment
- Electricity costs
- Trading software
- Research subscriptions
- Other operating expenses
The official rule states that no deduction is allowed except the cost of acquisition, where applicable.
This restriction makes accurate purchase records especially important. Investors should keep transaction statements showing the date, quantity, purchase value, and asset involved.
Crypto Losses Cannot Reduce Other Gains
One of the toughest parts of crypto tax in India is the treatment of losses.
A loss from one virtual digital asset cannot be set off against:
- Profit from another VDA
- Salary income
- Business income
- Property income
- Stock market gains
- Other taxable income
Crypto losses also cannot be carried forward to future years. Official guidance states that a VDA loss cannot be set off against other income or even against income from another VDA.
Example of the Loss Rule
Imagine that you make:
- ₹60,000 profit from Bitcoin
- ₹40,000 loss from another token
Under ordinary portfolio logic, your net gain would appear to be ₹20,000.
However, the VDA loss cannot be adjusted against the Bitcoin profit. The positive ₹60,000 income may still be taxed, while the ₹40,000 loss provides no tax relief.
Schedule VDA requires positive transaction income to be reported, while a loss from a transaction is reported as nil for the schedule’s final computation.
How the 1% Crypto TDS Works
Section 194S requires 1% TDS on consideration paid to a resident for transferring a virtual digital asset.
The important point is that TDS is normally calculated on the transaction value, not the profit.
For example, when crypto worth ₹1,40,000 is sold, the TDS may be ₹1,400 even when the actual profit is much lower.
The exchange may deduct the amount automatically when the transaction takes place through a compliant platform.
TDS Is Not an Additional Final Tax
TDS is an advance tax credit. It can normally be claimed while filing the income-tax return, provided the deduction appears correctly in the taxpayer’s records.
The final tax liability is calculated separately. A taxpayer may still owe additional tax when the final liability exceeds the TDS already collected.
Crypto TDS Thresholds in 2026
TDS is not required when the total consideration remains within the applicable annual threshold.
The threshold is:
- ₹50,000 for a specified person
- ₹10,000 for other payers
A specified person generally includes an individual or Hindu Undivided Family without business or professional income, or with turnover below the stated limits from the previous financial year.
These limits apply to TDS only. They do not create a general tax-free allowance for crypto profit.
A person may have taxable VDA income even when no TDS was deducted.
Are Crypto-to-Crypto Trades Taxable?
Exchanging Bitcoin for Ethereum or one token for another can be treated as a transfer of virtual digital assets.
The transaction does not become tax-free merely because Indian rupees were not received. The market value at the time of the swap may be needed to calculate the transfer income.
Official TDS guidance also explains that both sides may have withholding responsibilities when one VDA is exchanged for another, subject to how the transaction and platform are structured.
Beginners should keep records of:
- The assets exchanged
- Date and time
- Quantity of each asset
- Rupee market value
- Purchase cost
- Exchange charges
- TDS deducted
How Are Crypto Gifts Taxed?
Virtual digital assets are included within India’s tax rules for certain gifts.
When crypto is received without payment or for inadequate consideration, its value may become taxable under the income-from-other-sources provisions when the applicable conditions are met.
The rules contain exemptions for certain situations, including qualifying gifts from relatives, inheritance, and gifts received on specified occasions such as marriage. The exact treatment depends on the relationship, value, and circumstances.
The person selling gifted crypto later may also need the original acquisition information to complete Schedule VDA correctly.
Reporting Crypto in an Income-Tax Return
Taxpayers must report VDA transfers in Schedule VDA of the relevant income-tax return.
The schedule requests transaction-level information, including:
- Date of acquisition
- Date of transfer
- Cost of acquisition
- Sale consideration
- Resulting taxable income
- Applicable income head
The official 2026 Schedule VDA guidance says taxpayers must provide separate details for each transfer during the financial year.
ITR-2 and ITR-3 forms for the 2026 assessment year include specific reporting fields for income from virtual digital assets taxable at 30%. The correct return depends on whether the taxpayer has salary, capital gains, business income, or other sources of income.
Records Crypto Investors Should Keep
Crypto users should download records regularly instead of waiting until the tax-filing deadline.
Useful documents include:
- Exchange trade histories
- Wallet transaction records
- Bank statements
- TDS certificates or tax records
- Purchase invoices
- Deposit and withdrawal history
- Crypto-to-crypto swap details
- Gift documents
- Public wallet addresses
Transactions across several exchanges should be combined into one clear record.
Transfers between personal wallets should also be marked correctly. Moving crypto between wallets owned by the same person is different from selling it to another person, although network charges and missing records can make reconciliation difficult.
Common Crypto Tax Mistakes
Treating TDS as the Final Tax
The 1% TDS does not replace the 30% tax on taxable VDA income.
Adjusting One Token’s Loss Against Another Gain
Current rules do not permit this set-off.
Ignoring Crypto Swaps
Exchanging one cryptocurrency for another may still create a taxable transfer.
Reporting Only Bank Withdrawals
Tax liability may arise when crypto is transferred, even when the money remains on an exchange and is not withdrawn to a bank.
Failing to Match Exchange Records
Incorrect purchase prices, duplicate transactions, or missing wallet transfers can produce the wrong taxable amount.
Frequently Asked Questions
Is crypto legal in India in 2026?
Tax rules recognize and tax virtual digital asset transactions. However, paying tax does not mean every crypto product, platform, or activity has received government approval. Users must follow applicable financial, foreign-exchange, anti-money-laundering, and platform rules.
What is the crypto tax rate in India?
Income from transferring a VDA is generally taxed at 30%, plus applicable surcharge and 4% cess.
Is 1% TDS deducted from profit?
No. Section 194S generally applies 1% TDS to the transaction consideration rather than the profit.
Can crypto losses reduce Bitcoin profits?
No. A loss from one VDA cannot be set off against income from another VDA.
Is holding crypto without selling taxable?
The special 30% rule applies to income from transferring a VDA. Merely holding an asset without a transfer does not by itself create transfer income under Section 115BBH.
Do I need to report every crypto transaction?
Schedule VDA requires transaction-wise information for VDA transfers during the relevant financial year.
Conclusion
Crypto tax in India 2026 includes a 30% tax on income from VDA transfers, applicable surcharge and cess, and a separate 1% TDS system. Only the acquisition cost is generally deductible, while crypto losses cannot be adjusted against other income or carried forward.
